

How Dealerships Manipulate Interest Rates to Hide the Real Cost of a Warranty
Most people think the hardest part of buying a car is negotiating the price. It's not. The hard part is what happens after the price is agreed to. That's when you're handed off to the seemingly pleasant and chipper finance manager and the dealership's real games begin. That's also why we stay with our clients through this entire process, reviewing every document and every number so the traps and games don't go unnoticed.
In January 2025, we helped a client purchase a 2025 Toyota RAV4 Hybrid. We negotiated a great price with no add-on packages. The deal was clean. But the dealership wasn't.
What they tried next is something most car buyers would never catch. We caught it in real time while our client was sitting in the finance office.
The Original Deal
Our client financed $34,762.70. He qualified for Toyota's special financing rate of 5.99% on a 60-month loan (with plans to refinance right that same month). The dealership acknowledged this rate from the start. No dispute there.
He was also interested in an extended warranty. 8 years and 125,000 miles of coverage. Not unreasonable, based on his driving habits this made the most sense. He texted us what the dealership told him:
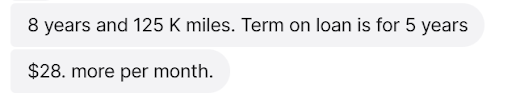
The text from our client, relaying what the dealership told him.
$28 a month for 8 total years of warranty coverage? That sounds like a no-brainer. And that's exactly how the dealership wanted it to sound.
Two Pieces of Paper, Two Different Rates
The dealership handed our client two documents.
The first was the preliminary purchase agreement, showing the loan terms without the warranty. It listed a monthly payment of $691 for 60 months.
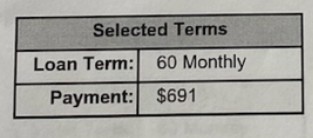
The preliminary purchase agreement. 60 months. $691 per month.
The second was the warranty "menu", showing the monthly payment with the extended warranty included. That number was $718.86 for 60 months.
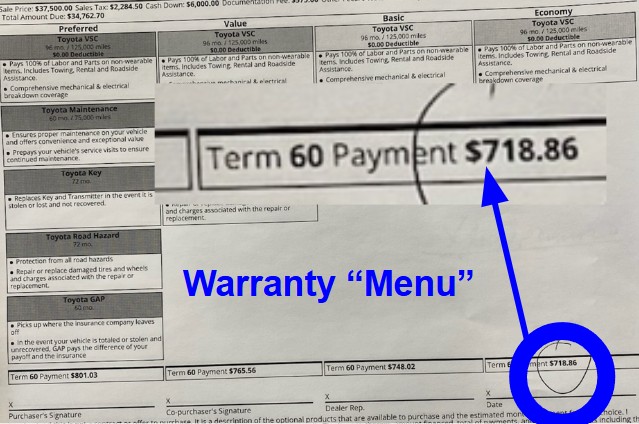
The warranty "menu." Same 60-month term. $718.86 per month with the warranty.
Do the math and it checks out: $718.86 minus $691 equals $27.86. Basically $28 a month, just like the dealership said. Seems fair. Seems transparent. Seems like a straightforward comparison.
It wasn't.
The $691 Payment Was Wrong
Here's the problem. Our client's approved interest rate was 5.99%. At 5.99% on $34,762.70 for 60 months, the correct monthly payment is $671.90.
Not $691. The dealership's purchase agreement was $19.10 higher than it should have been.
| Amount financed | $34,762.70 |
| Loan term | 60 months |
| Agreed interest rate | 5.99% |
| Correct monthly payment | $671.90 |
| Payment on the purchase agreement | $691.00 |
So where did $691 come from? We ran the numbers backward. A payment of $691 on a $34,762.70 loan for 60 months corresponds to an interest rate of approximately 7.2%.
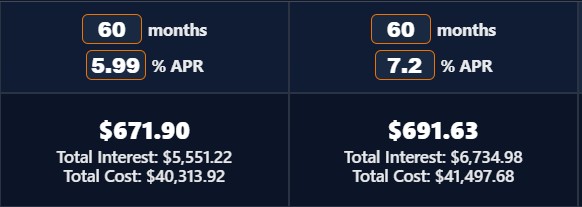
Same loan amount. Same term. Two different interest rates. The dealership used the number on the right.
The dealership used a 7.2% rate to calculate his payment (before the warranty was added), not the 5.99% rate our client was entitled to from the manufacturer. This inflated the base payment by about $19.73 per month. The warranty menu, meanwhile, used the correct 5.99% rate. Two documents. Two different rates. One purpose: to make the warranty look cheaper.
Why It Works
Think about what a buyer sees in the finance office. You're handed two options:
The buyer compares the two numbers side by side and sees a $27.86 difference. That's it. That's all they're looking at. Nobody pulls out a calculator to verify the base payment. Nobody checks whether both documents are using the same interest rate. You trust the paperwork.
But when you use the correct rate for both scenarios, the real comparison looks very different.
The Real Numbers
| Correct payment without warranty (5.99%) | $671.90 |
| Payment with warranty (5.99%) | $718.86 |
| Actual monthly cost of the warranty | $46.96 |
The warranty doesn't cost $28 a month. It costs $46.96 a month. The dealership closed that gap by inflating the base payment with a higher interest rate, so the jump to the warranty price looked smaller.
Here's what that difference looks like over the life of the loan:
| What the dealership told our client | $28 × 60 = $1,680 |
| What the warranty actually costs | $47 × 60 = $2,818 |
That's a $1,138 difference between what the buyer thinks they're paying and what they're actually paying, hidden in plain sight across two pieces of paper.
The dealership didn't lie about any single number. Every figure on every document was technically accurate. The trick was using different interest rates on different documents so the comparison between them told a misleading story.
We Caught It Before He Signed
We stay in contact with our clients during the entire car buying process, including while they're in the finance office. Our client sent us the documents and the numbers as they were presented to him. We ran the math, spotted the rate discrepancy, and let him know before he made a decision.
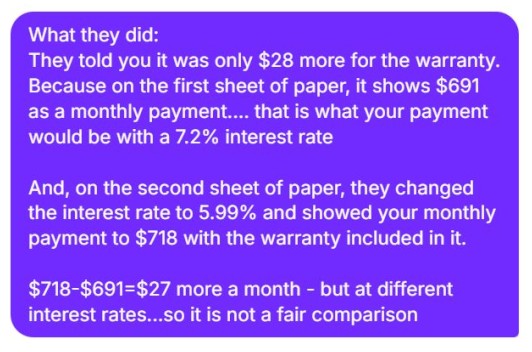
The message we sent our client, breaking down exactly what the dealership did.
This is rarely ever caught by car buyers. You just want to drive your new car home. The finance manager knows that. The entire process is designed around that moment. That's why we stay on standby for our clients through every step of the finance office, reviewing every number in real time so nothing slips through.
When you are ready for a new or used car, we'll help you do it the smart way, not the dealership's way.
Your Car. Your Terms. YourCarHaggler.com
Contact Your Car Haggler →